WhatsApp
 Pinterest
Child Education Goal Planner with SIP Calculator (Excel)
Work out what your child's engineering, MBBS, MBA or study-abroad will cost when they're ready, and the monthly SIP that gets you there, flat or rising with your income.
₹149₹349Save ₹200 (57%)
Inclusive of all taxes · One-time payment · Instant download
1 offer for you
Instant downloadOn screen + email
Secure paymentUPI · Cards · Net Banking
7-day helpFix or refund if faulty
Perfect for
Parents of young childrenParents planning for study abroadGrandparents who want to help
What you get2 × .xlsx (blank + sample)
Works withMicrosoft Excel · Google Sheets · WPS Office
DeliveryInstant download
LicencePersonal & own-business use
Frequently bought together
This item: Child Education Goal Planner with SIP Calculator (Excel)₹149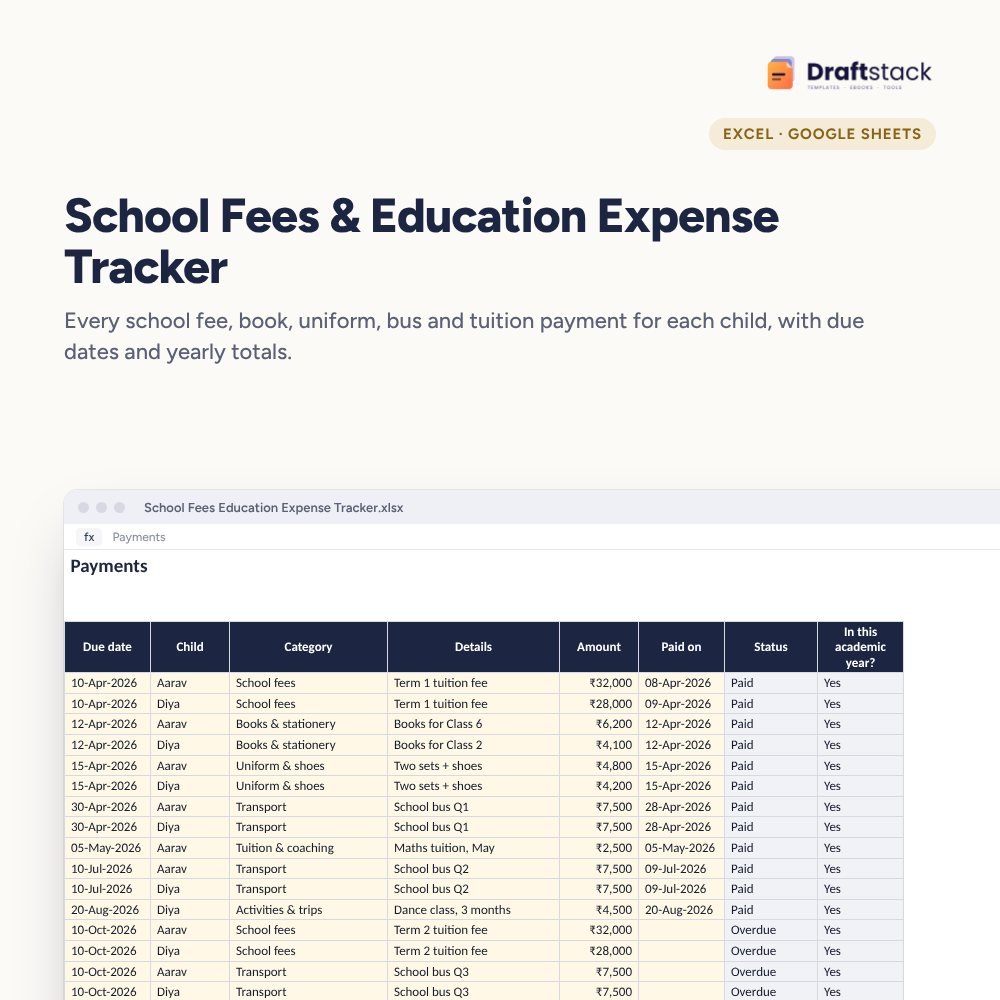 School Fees & Education Expense Tracker (Excel)₹129
 Retirement & Pension Planner (Excel): Fund Needed, Gap & Monthly SIP₹149
All three: ₹384₹427Extra 10% off
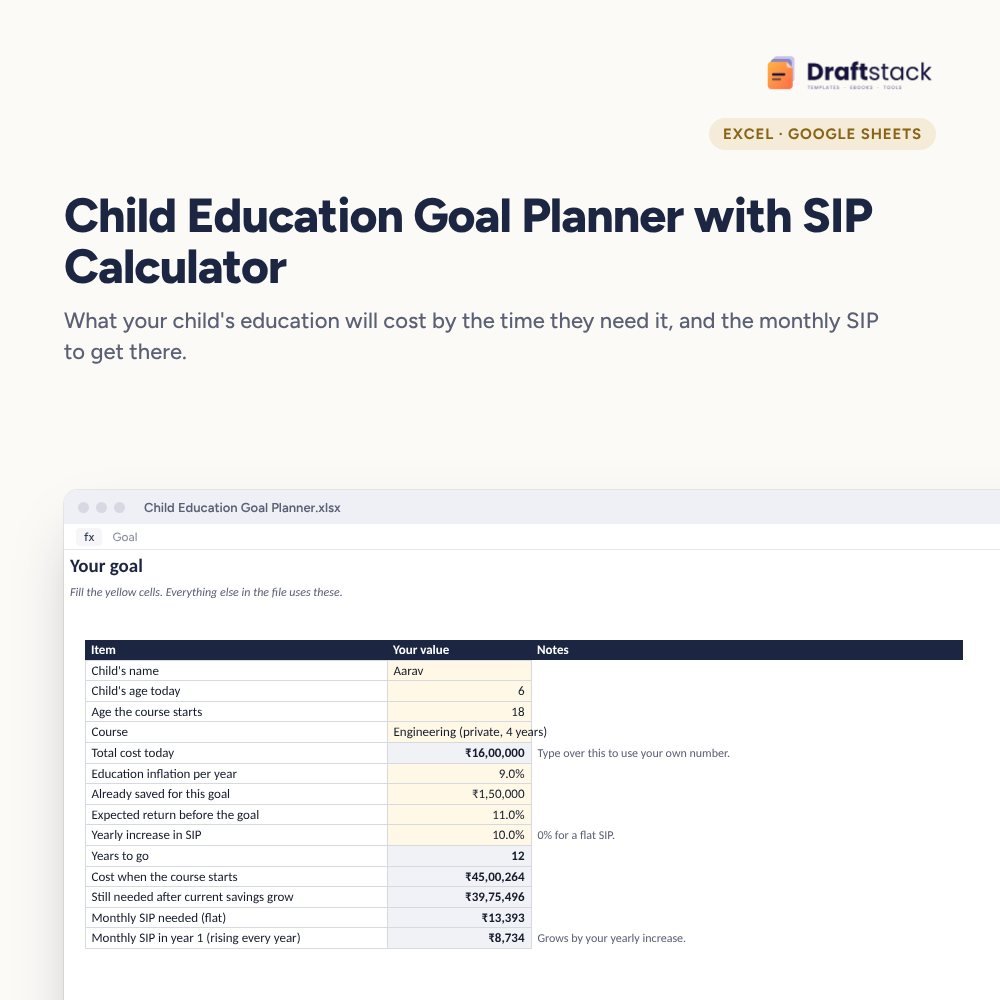
₹16 lakh for engineering today becomes over ₹40 lakh in 12 years at 9% education inflation. Most parents underestimate this, start late and end up with an education loan. A clear target early makes it easy.
What it does
- Course costs: engineering, MBBS, MBA, law, design, study abroad and more, as editable examples
- Future cost at your chosen education inflation
- Savings you already have, grown to the goal date
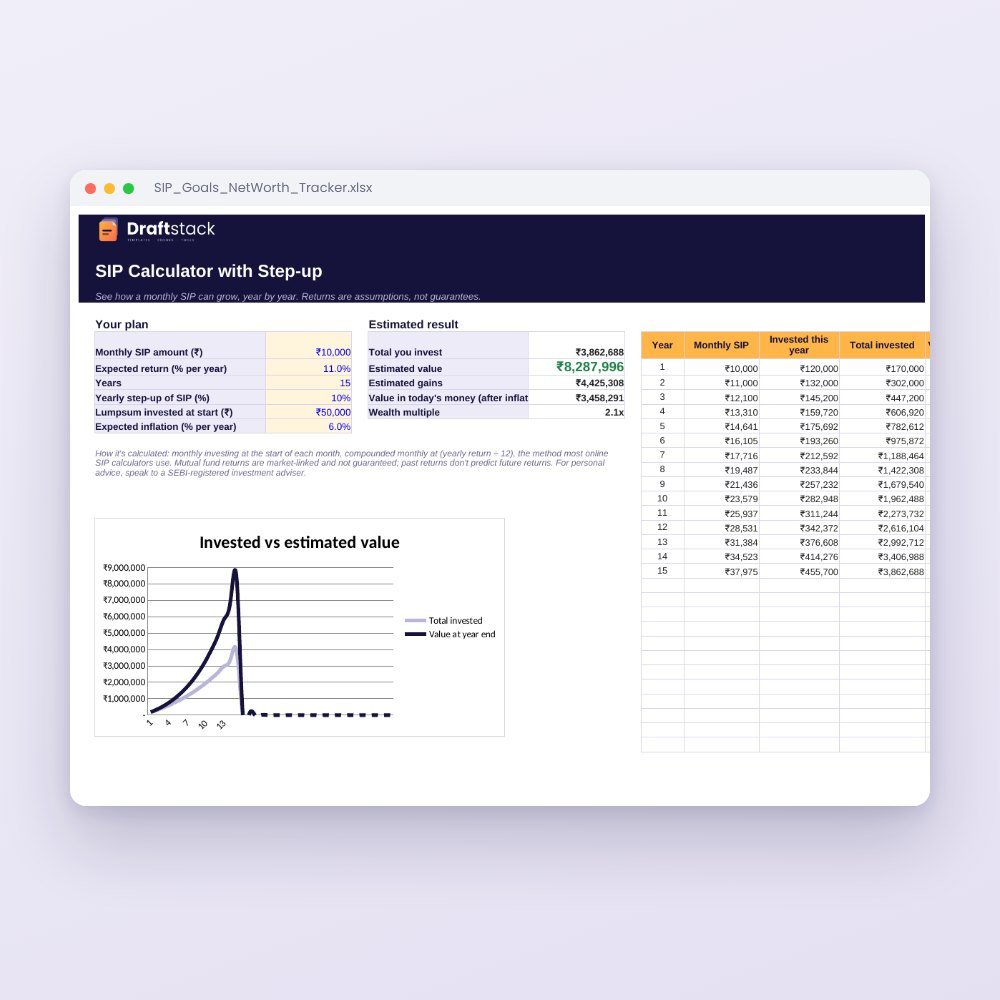
- Monthly SIP needed: flat, or starting lower and rising every year with your salary
- Year-by-year path: SIP, amount invested and fund value each year, with a chart
Plan for each child
Make a copy for each child or each goal (school, graduation, post-graduation). Seeing the numbers early lets you start small and stay steady.
What's inside
Everything you get
01
Goal sheet
Course, cost, years and SIP needed
02
Courses
Editable example costs
03
Plan
Year-by-year path with chart
04
Blank + sample
Sample for a 6-year-old
Files in your download
- XLSXChild_Education_Goal_Planner.xlsx14 KB
- XLSXChild_Education_Goal_Planner_SAMPLE.xlsx14 KB
How to use
Start in 5 simple steps
A step-by-step guide is also included inside your download.
- 1
Pick a course
Or type your own cost
- 2
Type ages
Today and at the start
- 3
Add savings
Already set aside
- 4
Choose a SIP style
Flat or rising
- 5
Review yearly
Raise SIP with income
FAQ
Questions about this product
What education inflation should I use?
8 to 10% is a common planning number for Indian private education. For studying abroad, add a little for the rupee.
What return should I expect?
For goals 7+ years away, equity funds have historically done better than FDs, with ups and downs. 10 to 12% is a common long-term assumption, not a promise.
Why is a rising SIP useful?
It starts lower and increases with your salary, which is easier for most families than a high flat SIP from day one.
Should I use Sukanya Samriddhi or PPF instead?
They're safe and tax-free and work well alongside SIPs, especially for part of the goal.
Can I plan for two children?
Yes. Make a copy of the file for each child.
How do I get the files after payment?
A download button appears on screen right after payment, and the link is emailed to you. You can also download again any time from My account.
Can I use it on my phone?
Yes. It works with Microsoft Excel, Google Sheets, WPS Office. Free mobile apps are enough.
What if something does not work?
Write to us within 7 days with your order number. We will fix it, send a working file, or refund you.
Our promiseEvery file is tested before launch. If something doesn't work, we fix it or refund you within 7 days. Refund policy
Complete the set
Goes well with this
 New
New
 New
Excel & Sheets
House Help Salary & Attendance Register (Excel): Maid, Cook, Driver, Nanny
₹99₹24960% off