How to Compare Personal Loan Offers (Look at APR, Not the Rate)
Personal loan ads show the interest rate in big letters. The fees, GST and insurance are in the fine print. To compare offers fairly, you need the total cost and the APR.
What makes up the cost
- Interest: worked out on the reducing balance; shows up in your EMI
- Processing fee: 0.5% to 3% of the loan, plus 18% GST
- Insurance: often added by default; usually optional
- Other charges: documentation, stamp duty, late payment and bounce charges
- Foreclosure charges: if you close early, often 2 to 5% of what's left
APR: the one number to compare
APR (annual percentage rate) is the yearly rate after including fees. Because fees are taken out on day one, you receive less than the loan amount but repay EMIs on the full amount. That pushes the real rate above the headline rate. RBI-regulated lenders must show the APR in the Key Fact Statement (KFS) before you sign.
A worked example: ₹5 lakh for 36 months
1. Bank A: 10.99%, 1.5% fee. EMI about ₹16,370; fees with GST ₹8,850; APR about 12.2%
2. NBFC B: 13.75%, 2% fee plus ₹3,500 insurance. EMI about ₹17,030; fees ₹15,300; APR about 15.9%
3. Bank C: 11.05%, 1% fee. EMI about ₹16,380; fees ₹5,900; APR about 11.9%
4. App D: 18%, 3% fee plus ₹1,200. EMI about ₹18,080; fees ₹18,900; APR over 20%
Bank C is cheapest even though Bank A's rate is lower, because of the smaller fee. The gap between the best and worst offers is over ₹70,000.
Red flags
- Lenders asking for an upfront "approval fee" before disbursal
- Apps that want access to your contacts and photos
- No clear name of the bank or NBFC lending the money
- Pressure to sign today
Borrow less, borrow smarter
1. Check if a top-up on your home loan or a loan against FD is cheaper.
2. Keep the EMI under about 15 to 20% of take-home pay if you already have other loans.
3. Choose the shortest tenure you can afford; it cuts total interest.
Before you sign, ask for these in writing
1. The Key Fact Statement with the APR
2. The full repayment schedule
3. Every fee, including GST, insurance and documentation charges
4. Foreclosure and part-prepayment rules
5. What happens if an EMI bounces: the charge and the penal interest
If any lender won't give these clearly, that alone is a good reason to choose another.
Our Personal Loan Comparison Sheet works out EMI, fees with GST, total cost and APR for up to eight offers and ranks them for you.
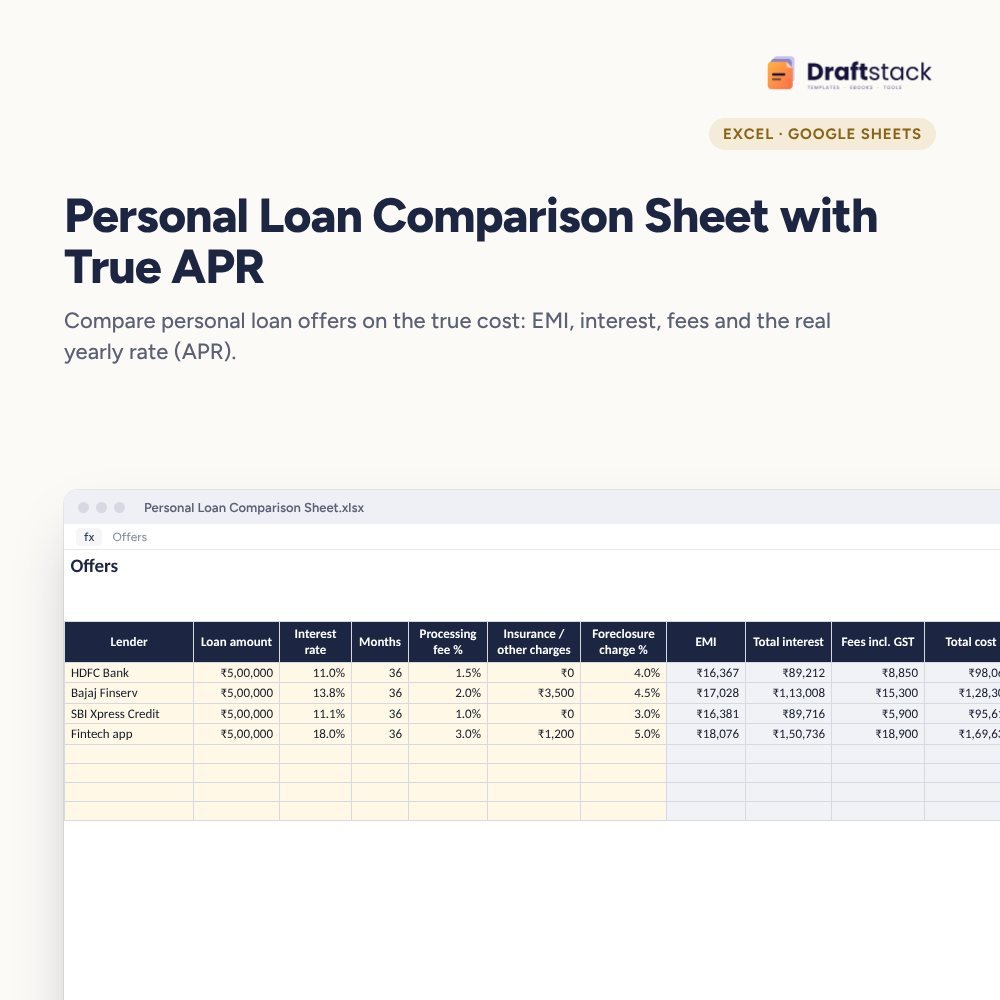 The template from this guidePersonal Loan Comparison Sheet with True APR (Excel)
₹99
 WhatsApp
Free Monthly Budget Sheet
A printable one-page budget sheet: income, fixed bills, daily spending and savings for the month. Print it or fill it on your phone.
More guides
Car Loan or Cash: Which Is Better for You?
How to compare a car loan with paying cash, why the flat rate trick matters, a worked example, and the questions to ask the dealer.
Rent vs Buy a House in India: How to Decide with Numbers
The real cost of buying (not just EMI), how to compare it fairly with renting, a worked example for an ₹85 lakh flat, and the questions to ask before you sign.
Income Tax for Freelancers in India: TDS, 44ADA and Advance Tax
How freelancers are taxed, how presumptive taxation works, what TDS means for you, when to pay advance tax, and a worked example for FY 2026-27.